If you’ve created a trust as part of your estate plan—congratulations! That’s a meaningful step toward protecting your assets and creating a legacy for your loved ones. One of the next decisions you’ll face is whether to open a separate bank account in the trust’s name or to continue managing trust-related funds through your personal bank account.
At Cary Estate Planning, we understand that this decision often raises more questions than answers. Rather than offering a one-size-fits-all rule, we help clients weigh the pros and cons of each option so they can make the best decision for their specific needs.
Separate Bank Account vs. Personal Account: What’s the Difference?
Let’s explore the key distinctions between maintaining a dedicated trust account and using your personal bank account to manage trust assets.
Option 1: Opening a Separate Bank Account for Your Trust
Opening a trust-specific bank account can provide the following benefits:
- Clear separation of assets: Keeping trust assets separate from personal funds may make it easier to demonstrate that the trust is functioning independently.
- Simplified recordkeeping: Having all income, expenses, and distributions run through a dedicated account often makes tracking activity more efficient—especially for trustees.
- Smoother administration: If you become incapacitated or pass away, your successor trustee may find it easier to step in and manage a distinct account that’s already set up in the trust’s name.
- Ease of tax reporting: For some trust structures, especially irrevocable trusts, having a dedicated account can help facilitate EIN-based tax reporting.
This option tends to work well for individuals who:
- Prefer to keep trust activity entirely separate from their own finances
- Have multiple trustees who need shared access to manage funds
- Want to simplify future administration for beneficiaries
Option 2: Using Your Personal Bank Account
Some clients choose to continue using their personal account when serving as both grantor and trustee of a revocable living trust. This can be convenient, especially when:
- The trust is newly created and not yet funded with many assets
- The trust will not have significant ongoing transactions
- The trustee prefers simplicity and is confident in their personal recordkeeping
However, there are trade-offs to be aware of:
- Personal and trust-related funds may commingle, which can create complications for future trustees or beneficiaries
- It may be more difficult to demonstrate which funds are owned by the trust vs. the individual, especially if questions arise during trust administration
- Successor trustees may need to transfer funds into a new account anyway after the grantor passes away
This approach may suit individuals who:
- Are the sole trustee and beneficiary during their lifetime
- Have minimal trust activity
- Are not concerned with administrative ease for future trustees
If You Decide to Open a Trust Bank Account
If you choose to open a bank account in your trust’s name, here’s what to expect.
Timing Matters
- If you’ve just created a living trust: Consider opening the account soon after to start transferring assets into the trust.
- If you’re a successor trustee: Opening an account will be necessary to handle financial matters on behalf of the trust after the grantor’s death.
What You’ll Need
- A copy of the trust document or a certification of trust
- Identification for all trustees (government-issued photo ID, Social Security numbers)
- Tax identification information (usually the grantor’s SSN for revocable trusts; an EIN for irrevocable trusts or after the grantor’s death)
- A death certificate, if the account is being opened posthumously
Steps to Take
- Choose a bank with experience handling trust accounts
- Schedule an appointment and ask what documents are required
- Bring all documents neatly organized
- Complete the application to title the account in the name of the trust
- Fund the account by transferring or depositing assets into it
Titling the Account Properly
One of the most important details is how the account is titled. The standard format is:
[Trustee Name], Trustee of the [Trust Name] dated [Trust Date]
For example:
“Jane Doe, Trustee of the Doe Family Trust dated February 1, 2024”
This ensures the account is legally recognized as being owned by the trust—not by you personally.
FAQs: Your Top Questions Answered
“Is a separate trust account required?”
No, not necessarily. Whether to open a separate account is a personal choice, and there’s no blanket legal requirement for all types of trusts. The decision often comes down to your goals, your comfort level with tracking finances, and your plan for administration.
“What kind of account can I open?”
That depends on how the trust will be used:
- Checking accounts for active trusts that need bill pay or distributions
- Savings or money market accounts for asset preservation
- Investment accounts for long-term growth
“Can I open the account at my current bank?”
Often, yes. Many clients find it convenient to open the trust account where they already bank, but it’s wise to compare fees, features, and experience with trusts.
“What happens if I don’t open a trust account?”
If you continue using your personal account, just be mindful of potential confusion during trust administration, especially if other people need to step in to manage your affairs.
Guidance for North Carolina Residents
North Carolina follows the Uniform Trust Code, which provides guidance on trustee duties and trust administration. While state law does not mandate a separate trust account, having one may help you fulfill your fiduciary duties—especially when it comes to transparency and recordkeeping.
At Cary Estate Planning, we help ensure your trust administration is fully aligned with North Carolina law and your long-term estate planning goals.
Let’s Talk About What’s Right for You
Whether you decide to open a trust bank account or not, the key is making an informed decision based on your unique situation.
At Cary Estate Planning, we’ll help you:
- Understand your responsibilities as a trustee
- Decide if a separate account makes sense for your trust
- Prepare any certification or supporting documents the bank may need
- Fund your trust properly so it works as intended
Have questions? We’re here to help.
Schedule a Discovery Call with our team today, and let’s ensure your trust is set up to serve you and your family for years to come.
This blog post is intended for informational purposes only and does not constitute legal advice. For personalized guidance, please contact our office to schedule a consultation with one of our experienced estate planning attorneys.
Author Bio
Paul Yokabitus
Founder & Estate Planning Lawyer
Paul Yokabitus is the founder of Cary Estate Planning, where he helps North Carolina families protect what matters most through wills, trusts, probate, and special needs planning. Known for his “planning, not paperwork” approach, Paul turns complex legal concepts into clear, practical strategies so clients feel informed and confident at every step. He has been recognized as a Business North Carolina Legal Elite attorney and a Super Lawyers Rising Star, and was named to the Triangle Business Journal’s 40 Under 40. A graduate of Campbell University School of Law, Paul lives in the Triangle with his wife, Alix, and their two sons.
Linkedin | Avvo | SuperLawyers



How We Help North Carolina Families


Paul and his team at Cary Estate Planning are fully committed to creating a personalized experience to develop thorough and comprehensive estate plans. They value their clients and go above and beyond to make sure that no details are missed. I would highly recommend Paul to anyone looking to create an estate plan.
I was referred to Paul by my Real Estate Attorney and I could not say enough about how exceptional the client service has been from everyone I spoke to. The communication is prompt and I feel like they really took the time to answer all my questions and set things up exactly as I wanted, but also recommended things to make it easier on my family down the line.
After attending one of Paul’s estate planning seminars, my husband and I knew we wanted Paul to assist us with our estate planning. His honest, professional approach to this necessary part of life put us at ease with the process. We will continue to recommend Paul and Cary Estate Planning.
We had a great experience working with Paul Yokabitus and the team at Cary Estate Planning to set up our Will and Estate Plan. The process was clear and easy, and in the age of COVID, our signing session was very well done, easy, and safe.
The Cary Estate Planning team will make sure that you have the information you need to be confident in your estate planning decisions. I learned so much from videos, a one-on-one in-person consultation, the website, emails, and a newsletter mailed the old fashioned way. The fee is very reasonable given the importance of estate planning. No matter the size or number of your assets, don’t procrastinate like I did!
Paul is a masterful attorney. He’s very good at taking your intentions and defining that into a durable Trust and Will. Best of all he is as simple and plain-spoken as you like. Or as fast as intellectual as you may be. It’s all about your your speed and your desired outcomes. Would strongly recommend this firm.
Trusted Estate Planning
Attorney Offices in Cary and Raleigh
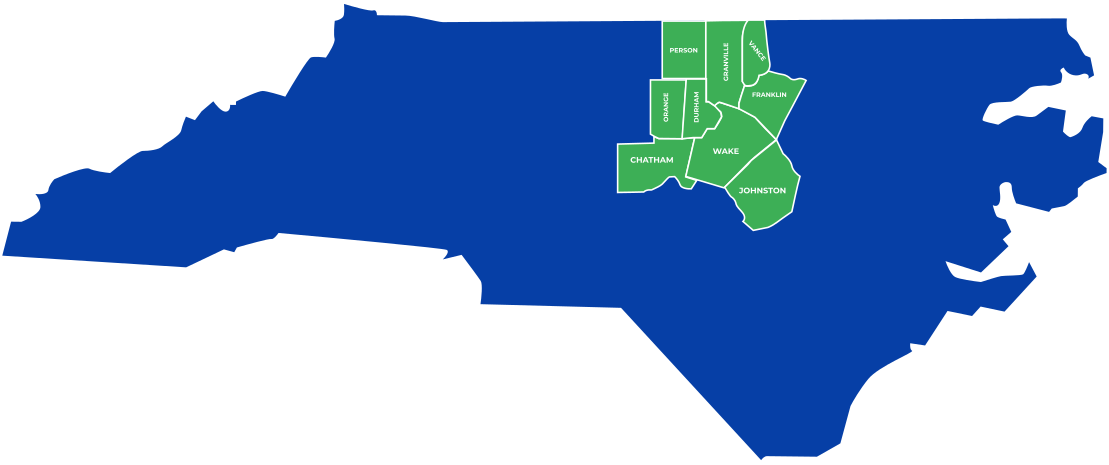

Capability to meet virtually to help all NC residents