When someone passes away, their debts do not automatically disappear. The bills become claims against the estate, and the personal representative is responsible for sorting out which ones get paid and which do not. Family members are usually not personally responsible for the deceased person’s debts, with a few important exceptions.
Knowing how unpaid bills are handled in North Carolina helps you protect the estate, the beneficiaries, and yourself.
Who Pays the Bills After Someone Dies in NC?
The estate pays the bills, not the family. Once probate opens, the executor or administrator uses estate assets to pay valid debts in the order set by N.C. Gen. Stat. § 28A-19-6. Surviving family members are generally not on the hook unless they:
- Co-signed the debt or held the account jointly
- Were married to the deceased and the debt was incurred for necessary household expenses
- Inherited a specific asset that secured the debt, like a mortgaged home
North Carolina is not a community property state, so a surviving spouse does not automatically inherit credit card balances or personal loans the deceased held alone.
How the Estate Handles Unpaid Bills
The personal representative follows a defined process under Chapter 28A of the General Statutes:
- Open the estate with the clerk of superior court in the county where the deceased lived
- Inventory the estate’s assets and value them as of the date of death
- Publish notice to creditors in a local newspaper for four consecutive weeks
- Send a written notice to known creditors directly
- Review and either accept or reject each claim filed within 90 days of first publication
- Pay valid claims in the statutory priority order
- Distribute what remains to the beneficiaries
Creditors that miss the 90-day deadline are barred under N.C. Gen. Stat. § 28A-19-3. The In re Estate of Taylor decision (242 N.C. App. 30) confirmed that even funeral expenses must be filed within this window, with no automatic exemption.
Priority Order for Paying Estate Debts
If the estate does not have enough money to pay every bill, North Carolina law sets the order under § 28A-19-6. After paying costs and expenses of administration, the remaining claims are paid in this order:
- First class: Claims with a specific lien on property, up to the value of that property
- Second class: Funeral expenses up to $3,500
- Third class: Gravestones and burial place costs up to $1,500
- Fourth class: Federal taxes and other federal preferences
- Fifth class: State, county, and municipal taxes
- Sixth class: Judgments docketed against the deceased
- Seventh class: Wages owed to employees within twelve months before death
- Eighth class: Medical services for the last illness
- Ninth class: All other claims
Executors who pay lower-priority bills before higher ones can be held personally liable to the creditors who got shortchanged. This is one of the most common probate mistakes.
What Happens to Specific Types of Bills?
Different debts get treated differently after death:
- Credit cards: Unsecured. Paid by the estate if assets allow. If not, the balance is written off.
- Medical bills: Treated as a claim like any other, though last-illness expenses receive priority status.
- Mortgages: The lien stays attached to the home. Heirs who want to keep the property must continue payments or refinance.
- Car loans: The vehicle secures the debt. If no one keeps making payments, the lender can repossess.
- Utility bills: Paid from the estate while accounts are active, then closed once the property transfers or sells.
- Federal student loans: Discharged at death for the borrower. Private student loans depend on the lender’s terms.
- Tax debts: The IRS and North Carolina Department of Revenue can claim against the estate for unpaid income, estate, or inheritance taxes.
Are Family Members Ever Liable for Bills?
Generally, no, but watch for these situations where personal liability does come into play:
- Joint accounts: If you co-signed or were a joint account holder, the lender can pursue you for the full balance.
- Authorized users: Generally not liable, but the line between authorized user and joint holder gets blurry. Check the original account documents.
- Spousal liability for necessities: North Carolina recognizes the doctrine of necessaries, which can make a surviving spouse liable for medical bills and other necessary expenses incurred during the marriage.
- Improper distributions: If you receive estate property before debts are paid and the estate runs short, you may have to return what you got.
What if the Estate Cannot Pay Every Bill?
This is called an insolvent estate. The personal representative pays as far as the priority list allows, and unpaid lower-priority debts are simply discharged. Creditors cannot then go after beneficiaries or family members for the difference unless one of the personal-liability exceptions applies.
Insolvent estates require careful documentation. The personal representative files a final accounting showing exactly which claims were paid, in what order, and how the remaining assets ran out. Skipping steps here invites both creditor lawsuits and clerk objections.
Manage Estate Debts Without Personal Risk
Sorting through a deceased loved one’s bills is stressful. Our attorneys handle the notice process, claim review, and payment priorities so the estate stays compliant and your family is protected.
Schedule a Discovery Call to talk through your situation. From there, we recommend an Initial Strategy Meeting with one of our attorneys to map out a personalized plan and walk through pricing.
We proudly serve all of North Carolina, with attorneys based in Cary and Raleigh. Contact us today to get started.
Author Bio
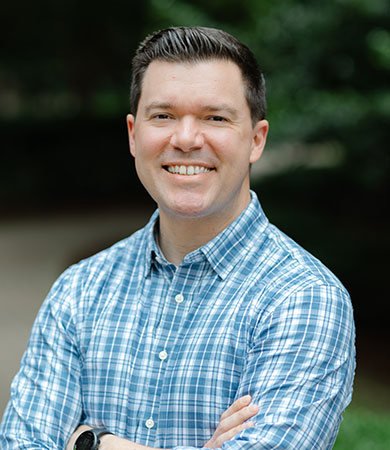
Paul Yokabitus
Founder & Estate Planning Lawyer
Paul Yokabitus is the founder of Cary Estate Planning, where he helps North Carolina families protect what matters most through wills, trusts, probate, and special needs planning. Known for his “planning, not paperwork” approach, Paul turns complex legal concepts into clear, practical strategies so clients feel informed and confident at every step. He has been recognized as a Business North Carolina Legal Elite attorney and a Super Lawyers Rising Star, and was named to the Triangle Business Journal’s 40 Under 40. A graduate of Campbell University School of Law, Paul lives in the Triangle with his wife, Alix, and their two sons.
Linkedin | Avvo | SuperLawyers



How We Help North Carolina Families


Paul and his team at Cary Estate Planning are fully committed to creating a personalized experience to develop thorough and comprehensive estate plans. They value their clients and go above and beyond to make sure that no details are missed. I would highly recommend Paul to anyone looking to create an estate plan.
I was referred to Paul by my Real Estate Attorney and I could not say enough about how exceptional the client service has been from everyone I spoke to. The communication is prompt and I feel like they really took the time to answer all my questions and set things up exactly as I wanted, but also recommended things to make it easier on my family down the line.
After attending one of Paul’s estate planning seminars, my husband and I knew we wanted Paul to assist us with our estate planning. His honest, professional approach to this necessary part of life put us at ease with the process. We will continue to recommend Paul and Cary Estate Planning.
We had a great experience working with Paul Yokabitus and the team at Cary Estate Planning to set up our Will and Estate Plan. The process was clear and easy, and in the age of COVID, our signing session was very well done, easy, and safe.
The Cary Estate Planning team will make sure that you have the information you need to be confident in your estate planning decisions. I learned so much from videos, a one-on-one in-person consultation, the website, emails, and a newsletter mailed the old fashioned way. The fee is very reasonable given the importance of estate planning. No matter the size or number of your assets, don’t procrastinate like I did!
Paul is a masterful attorney. He’s very good at taking your intentions and defining that into a durable Trust and Will. Best of all he is as simple and plain-spoken as you like. Or as fast as intellectual as you may be. It’s all about your your speed and your desired outcomes. Would strongly recommend this firm.
Trusted Estate Planning
Attorney Offices in Cary and Raleigh
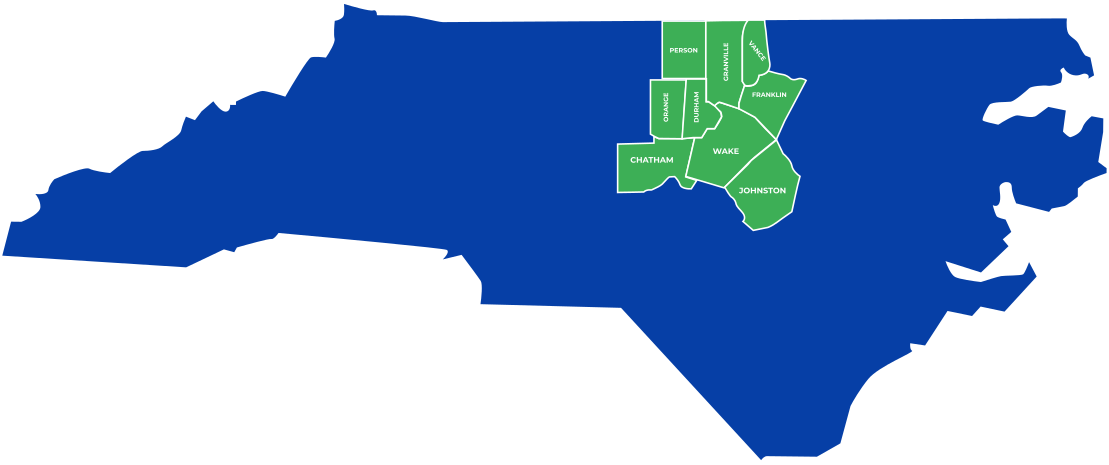

Capability to meet virtually to help all NC residents