Collecting life insurance almost certainly requires a certified death certificate, but if you do not have one yet, you can still get the process moving. You can start the claim, gather the other required documents, and work with the insurer while the certified death certificate is being issued. Knowing what to do in the meantime keeps the claim from stalling.
Why Insurers Ask for a Death Certificate
A life insurance payout is often a large sum, so insurers verify that a death actually occurred before releasing funds. The certified death certificate is the standard proof. It confirms the death, the date, and the cause, which the insurer needs to process the claim and rule out issues.
Because of this, most insurers will not release payment on a certified-copy basis without it. The good news is that a certified death certificate is usually available within a couple of weeks of the death, and often sooner, so the wait is typically short.
What You Can Do Before the Certificate Arrives
Not having the certified death certificate in hand yet does not mean you have to sit and wait. You can move several steps forward:
- Locate the life insurance policy documents and note the policy number
- Contact the insurance company to report the death and open a claim
- Ask the insurer exactly what they require and request their claim forms
- Complete the claim forms with the information you have
- Gather other supporting documents the insurer asks for
- Confirm who the named beneficiary is on the policy
Starting early means that once the certified death certificate is ready, you can submit a complete package rather than beginning from scratch.
How to Get the Death Certificate Quickly
Since the certificate is the key document, getting certified copies promptly helps everything move. In North Carolina, certified death certificates are available through the register of deeds in the county where the death occurred, or through the state vital records office.
A few tips:
- Order several certified copies at once, since banks, insurers, and agencies each want one
- The funeral home can often order copies for you as part of their services
- Confirm whether the insurer needs a certified copy or will accept another format to begin
Ordering extra certified copies up front saves repeated trips later, because nearly every institution involved in settling an estate will ask for one.
Who Can Collect the Life Insurance?
Life insurance usually passes outside the estate, straight to the named beneficiary. This is one reason it often reaches the family faster than assets that go through probate. Who collects depends on the beneficiary designation:
- A named living beneficiary files the claim and receives the money directly
- Multiple beneficiaries each file for their share
- No living beneficiary, or the estate named as beneficiary, means the proceeds go to the estate and are handled by the personal representative
Because a named beneficiary collects directly, that person usually does not need to open probate just to claim the policy. They deal with the insurer, not the court.
What If the Estate Is the Beneficiary?
Sometimes a policy names the estate as beneficiary, or all named beneficiaries have died. In that case the proceeds become an estate asset. To collect, the personal representative generally needs:
- Certified letters testamentary or letters of administration
- A certified death certificate
- The insurer’s claim forms
The money then flows into the estate and is distributed along with other estate assets. This is a different path from a named beneficiary collecting directly, and it does involve the estate process.
What If You Cannot Find the Policy?
Sometimes families know a policy exists but cannot find the paperwork. Steps that help locate a missing policy include:
- Checking the deceased person’s financial records, bank statements for premium payments, and email
- Contacting their employer or former employer about group life coverage
- Reviewing tax returns for any related information
- Using a policy locator service that searches participating insurers
- Checking with the state’s unclaimed property office for unclaimed benefits
Persistence pays off here. Group life insurance through an employer is especially easy to overlook, so it is worth asking.
Avoiding Delays in the Claim
A few practical habits keep a life insurance claim moving smoothly:
- Order plenty of certified death certificates early
- Respond quickly to any insurer requests for information
- Keep copies of everything you submit
- Confirm the beneficiary designation is current and clear
- Follow up if you do not hear back within the insurer’s stated timeframe
Most life insurance claims are paid within a matter of weeks once the insurer has a complete package, including the certified death certificate.
How Long Does a Claim Usually Take?
Once the insurer has a complete claim package, including the certified death certificate, many life insurance claims are paid within a few weeks. Several things can affect the timing:
- Whether the beneficiary designation is clear and current
- Whether the death occurred within the policy’s contestability period, which can prompt extra review
- How quickly the beneficiary returns the insurer’s forms
- Whether the estate, rather than a named person, is the beneficiary
For a straightforward claim with a clearly named beneficiary, payment is often quick. When the estate is involved, expect the timeline to track the pace of settling the estate more generally, since the personal representative has to be appointed first.
Keep Good Records
Throughout the claim, keep copies of every form you submit and note who you spoke with and when. A simple record prevents confusion if the insurer asks for something twice, and it gives the family a clear trail to rely on.
Keeping the Claim on Track
You generally cannot finish a life insurance claim without a certified death certificate, but you do not have to wait idly for it either. Start the claim, gather the documents, and order certified copies promptly so everything comes together quickly. Our attorneys can help families coordinate life insurance claims alongside the rest of settling an estate.
If you are working through a loved one’s affairs and want help keeping everything on track, our attorneys are here for you.
Contact us to get started.
Author Bio
Paul Yokabitus
Founder & Estate Planning Lawyer
Paul Yokabitus is the founder of Cary Estate Planning, where he helps North Carolina families protect what matters most through wills, trusts, probate, and special needs planning. Known for his “planning, not paperwork” approach, Paul turns complex legal concepts into clear, practical strategies so clients feel informed and confident at every step. He has been recognized as a Business North Carolina Legal Elite attorney and a Super Lawyers Rising Star, and was named to the Triangle Business Journal’s 40 Under 40. A graduate of Campbell University School of Law, Paul lives in the Triangle with his wife, Alix, and their two sons.
Linkedin | Avvo | SuperLawyers



How We Help North Carolina Families


Paul and his team at Cary Estate Planning are fully committed to creating a personalized experience to develop thorough and comprehensive estate plans. They value their clients and go above and beyond to make sure that no details are missed. I would highly recommend Paul to anyone looking to create an estate plan.
I was referred to Paul by my Real Estate Attorney and I could not say enough about how exceptional the client service has been from everyone I spoke to. The communication is prompt and I feel like they really took the time to answer all my questions and set things up exactly as I wanted, but also recommended things to make it easier on my family down the line.
After attending one of Paul’s estate planning seminars, my husband and I knew we wanted Paul to assist us with our estate planning. His honest, professional approach to this necessary part of life put us at ease with the process. We will continue to recommend Paul and Cary Estate Planning.
We had a great experience working with Paul Yokabitus and the team at Cary Estate Planning to set up our Will and Estate Plan. The process was clear and easy, and in the age of COVID, our signing session was very well done, easy, and safe.
The Cary Estate Planning team will make sure that you have the information you need to be confident in your estate planning decisions. I learned so much from videos, a one-on-one in-person consultation, the website, emails, and a newsletter mailed the old fashioned way. The fee is very reasonable given the importance of estate planning. No matter the size or number of your assets, don’t procrastinate like I did!
Paul is a masterful attorney. He’s very good at taking your intentions and defining that into a durable Trust and Will. Best of all he is as simple and plain-spoken as you like. Or as fast as intellectual as you may be. It’s all about your your speed and your desired outcomes. Would strongly recommend this firm.
Trusted Estate Planning
Attorney Offices in Cary and Raleigh
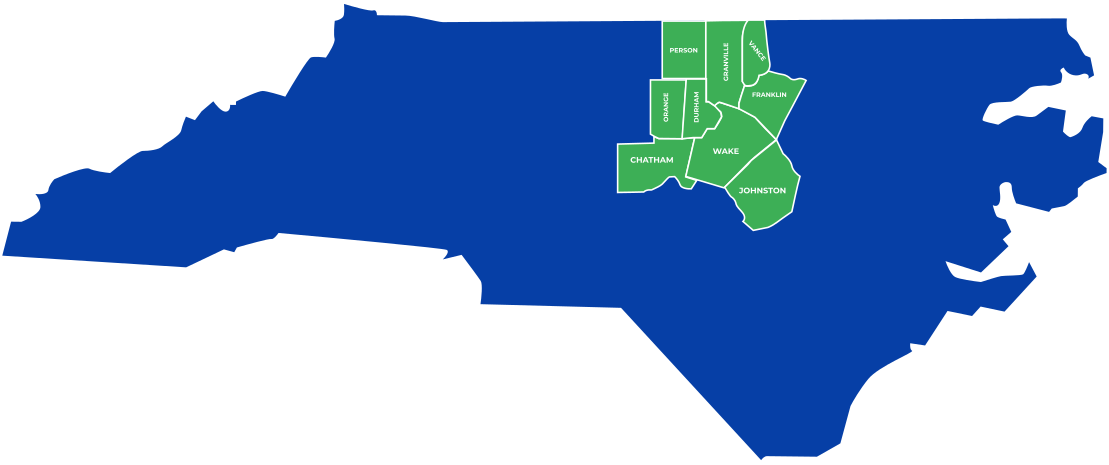

Capability to meet virtually to help all NC residents