Short answer: Maybe, but it depends.
Long answer: there are specific rules that must be followed in order to have a trust be a beneficiary of a qualified retirement plan. 401k’s and 403b’s cannot have a non-human beneficiary, but IRA’s can. However, the trust must meet the following four requirements:
1. The trust must be valid under state law;
2. The trust must be irrevocable (or become irrevocable at the death of the plan participant);
3. The trust beneficiaries and their ages must be identifiable; and
4. The trust documentation must be provided to the plan administrator by October 31 of the year following the participant’s death.
This type of trust is call a “See Through Trust”. There are pros and cons to using a trust as a beneficiary of your IRA.
Pros – a trust is best used in the scenario where the potential beneficiaries of the IRA are minor children. Federal law does not allow minors to inherit such benefits outright until they reach the age of majority. The funds received from the IRA would ultimately need to be held in trust anyway. If used appropriately, the trust could be used to stretch out the IRA distributions over the life of the beneficiary, rather than being subject to the 5 Year Rule (requiring the entire plan balance to be distributed within 5 years of the death of the plan participant). If the STT is a “Conduit Trust” – meaning it acts as a pass through tax entity and the income is attributed to the beneficiary for tax purposes – you could still achieve favorable tax treatment even with the trust.
Cons – Trusts are taxed at a higher rate than most people realize. The top income tax rate on trusts for 2016 is around 40% (which is the same as the top tax rate for the federal estate and gift tax). If the trustee elects to take a lump sum distribution in the first year, the whole distribution would be taxed at 40%, meaning you basically just had the estate tax applied to your retirement account, except it’s going to have to be paid by your beneficiaries rather than your estate. Naming individual beneficiaries of your IRA allows them to take income distributions at their individual income tax rate, which is likely much lower than 40%. Additionally, if the STT is an “Accumulation Trust” – meaning it receives the IRA required minimum distributions (“RMDs”) and holds them before disbursing income to the beneficiaries – the RMD income will be taxed at the trust level instead and subject to much less favorable tax treatment.
Ultimately, IRA trust planning is complex and requires a case-by-case analysis of each family’s financial situation and desires. Do not take this sort of planning lightly.
Author Bio
Paul Yokabitus
Founder & Estate Planning Lawyer
Paul Yokabitus is the founder of Cary Estate Planning, where he helps North Carolina families protect what matters most through wills, trusts, probate, and special needs planning. Known for his “planning, not paperwork” approach, Paul turns complex legal concepts into clear, practical strategies so clients feel informed and confident at every step. He has been recognized as a Business North Carolina Legal Elite attorney and a Super Lawyers Rising Star, and was named to the Triangle Business Journal’s 40 Under 40. A graduate of Campbell University School of Law, Paul lives in the Triangle with his wife, Alix, and their two sons.
Linkedin | Avvo | SuperLawyers



How We Help North Carolina Families


Paul and his team at Cary Estate Planning are fully committed to creating a personalized experience to develop thorough and comprehensive estate plans. They value their clients and go above and beyond to make sure that no details are missed. I would highly recommend Paul to anyone looking to create an estate plan.
I was referred to Paul by my Real Estate Attorney and I could not say enough about how exceptional the client service has been from everyone I spoke to. The communication is prompt and I feel like they really took the time to answer all my questions and set things up exactly as I wanted, but also recommended things to make it easier on my family down the line.
After attending one of Paul’s estate planning seminars, my husband and I knew we wanted Paul to assist us with our estate planning. His honest, professional approach to this necessary part of life put us at ease with the process. We will continue to recommend Paul and Cary Estate Planning.
We had a great experience working with Paul Yokabitus and the team at Cary Estate Planning to set up our Will and Estate Plan. The process was clear and easy, and in the age of COVID, our signing session was very well done, easy, and safe.
The Cary Estate Planning team will make sure that you have the information you need to be confident in your estate planning decisions. I learned so much from videos, a one-on-one in-person consultation, the website, emails, and a newsletter mailed the old fashioned way. The fee is very reasonable given the importance of estate planning. No matter the size or number of your assets, don’t procrastinate like I did!
Paul is a masterful attorney. He’s very good at taking your intentions and defining that into a durable Trust and Will. Best of all he is as simple and plain-spoken as you like. Or as fast as intellectual as you may be. It’s all about your your speed and your desired outcomes. Would strongly recommend this firm.
Trusted Estate Planning
Attorney Offices in Cary and Raleigh
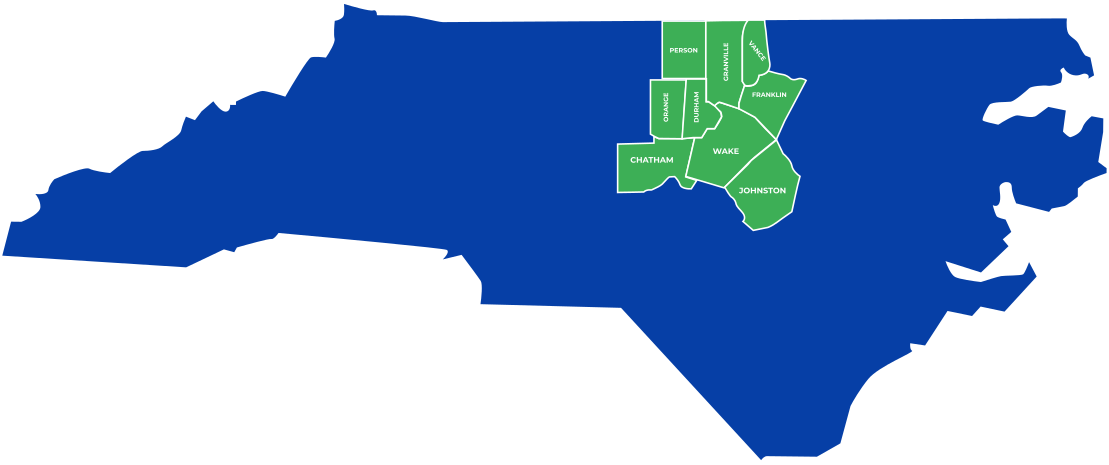

Capability to meet virtually to help all NC residents